
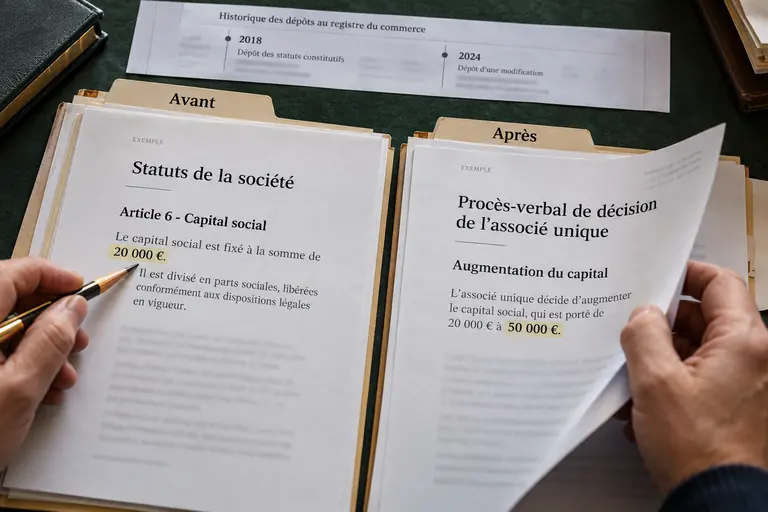
In Spain, the commercial register completes share capital increase registration only once a vote to raise capital has been turned into a notarial deed, and until then the change means nothing to outsiders. After the shareholders approve the operation and the new contributions or reserves are in place, the increase is formalised in a public deed and presented to the registrar. The registrar checks legality and, if satisfied, records the higher capital figure together with the new shares or holdings, so that creditors, partners and the public can see the company's updated financial base.
Ways a company can raise its capital
A Spanish company can increase its capital by issuing new shares or by raising the nominal value of the existing ones. The money can come from new contributions in cash or in kind, from converting claims against the company into equity, or from turning reserves and profits into capital without any outside funding. Each route has distinct formal requirements and different consequences for the shareholders. New cash contributions strengthen the company's funds and bring in fresh resources.
Contributions in kind, such as property or a business, normally call for a valuation and an independent report for certain company types, because the registry and creditors need assurance that the assets are worth what the company says. Capitalising reserves, by contrast, does not alter total equity but changes its composition, moving amounts from freely available reserves into capital that is harder to distribute.
Set-off of debts has its own checks, because the claim converted must be certain, due and payable for the operation to be valid. Deciding which route fits is not purely a legal exercise. A company short of cash needs fresh money, while a company with healthy reserves may simply want a larger capital base to reassure lenders. The reason for the increase also shapes the price of new shares, the timetable and the information given to shareholders.
Shareholder decision and preferential rights
The capital increase is normally decided by the general meeting under the majorities and formalities required for amending the statutes, although the administrators can sometimes be authorised to carry it out within limits. Notice of the meeting should specify the proposal, and the administrators typically prepare a report explaining it. Existing shareholders usually hold a preferential right to subscribe the new shares or to assume the new holdings in proportion to their stake, so that their percentage is not diluted without consent. That right can be excluded only in cases and with safeguards set by the law, which include a justified report.
Practical matters follow from the resolution: the period for exercising preferential rights, the price per share including any premium, the way contributions are to be made and what happens if the increase is only partly subscribed. A carefully drafted agreement avoids disputes about any of these points later. Shareholders who do not wish to invest more can sometimes sell their preferential rights, where the type of company allows it, or accept dilution. Agreements between partners may add rules of their own, so the shareholders' agreement should be consulted alongside the articles before the meeting takes place.
Paying in the contributions
Before the deed is signed, the contributions must be actually delivered according to the resolution. Cash is paid into a bank account of the company, and the bank issues a certificate that the notary can examine. Assets in kind are transferred, and the company must be able to show that the transfer is effective. Where the law requires a report or a valuation, it should be ready before the deed. Dates matter, since the valuation should be recent enough to be reliable at the time the operation is formalised. The company should keep supporting documents available for the notary and the registrar.
If capital is increased by capitalising reserves, the accounts or a balance sheet closely preceding the resolution generally serve as the basis. The reserves used must be available and reflected in verified statements, which is why companies should not decide on such an operation without reviewing their latest approved or audited figures. Contributions in kind raise a further point: the asset must be transferable to the company and free of encumbrances that would defeat its purpose. A property with a mortgage, for instance, needs careful handling, and the deed should describe the asset precisely enough to be identified in other public records.
The notarial deed and its content
The increase is formalised in a public deed signed before a notary. The deed states the agreement adopted, the amount and manner of the increase, the identity of those who subscribed and paid, and the new wording of the statutory clause on capital and shares. The notary verifies the legality of the formalities and the identity of the parties. If the company is a public limited company, there are additional elements such as the nominal value of shares, their numbering and the rights attached to each class. For limited liability companies the deed refers to the holdings created or increased, with their numbering and the owners of each one.
The deed also records the contributions made and the evidence of payment. Careful review of the draft with the administrators helps avoid mistakes in the figures, which are among the commonest reasons for a registrar to suspend or refuse the filing. After signing, the notary issues authorised copies, and the deed should be sent for registration without unnecessary delay. A long gap between signature and filing leaves the company in an uncertain state, because the increase exists in the books but is not yet opposable to third parties.
Presentation to the registrar and what is entered
The deed is presented to the commercial registry of the company's registered office, usually by electronic means. The registrar qualifies the deed, examining its legality, the competence of the decision-maker, the validity of the formalities and the compatibility with what the registry already shows about the company. If everything is in order, the registrar enters the new amount of capital and the corresponding changes in shares or holdings, and the entry is published in the official bulletin of the registry. From then on, third parties can rely on the new capital figure, and the company can show it in extracts and certificates.
Where the registrar identifies defects, a notice sets out the reasons and the company can correct them within the period allowed. Examples include missing evidence of payment, an inconsistent figure in the clause or a lack of authority for the person who certified the resolution. Companies sometimes ask whether they may use the new capital before the entry is made. The answer depends on the circumstances, but acting as if the increase were complete while the registration is pending can create exposure, so administrators generally wait until the entry is confirmed before announcing the new figure.
Consequences, risks and points to confirm
Once registered, a larger capital changes the company's profile. It can improve credibility with banks and suppliers, enable growth, or form part of a restructuring after losses. It may also alter voting power and the share of profits, so each shareholder should understand the effect on their stake before approving it. Tax and accounting treatment depend on the form of the operation and on the nature of the contributions. A company should confirm with its advisers how the increase is recorded and which taxes or formalities apply, because rules are updated and the answer is not the same for every structure.
This is general information and not advice on a specific transaction. Because details such as majorities, content of reports and registry practice are set by current law and by the registrars' instructions, they should be checked at the time of the operation with a lawyer experienced in Spanish company filings. It also helps to update the shareholders' register after registration. The ledger of shares or holdings must show the new numbering and owners, and certificates or confirmations given to investors should match the entry in the registry exactly.
Frequently asked questions
When does a capital increase take effect against third parties?
Third parties can rely on it once it is entered in the commercial register and published in the official bulletin. The shareholders' resolution and the notarial deed matter internally, but the registry entry is what makes the new figure official for creditors and the public.
Do existing shareholders get priority to subscribe?
Usually yes. Shareholders generally hold a preferential subscription right in proportion to their stake, which protects them from dilution. It can be excluded only under the conditions the law sets, typically with a justified report, so the resolution should state clearly how that right is handled.
Can reserves be turned into capital?
Yes, a company may capitalise available reserves or profits, subject to verified accounts and the statutory formalities. Total equity stays the same, but the amount moves into capital. The deed and the registry filing follow the same route as other capital increases.