
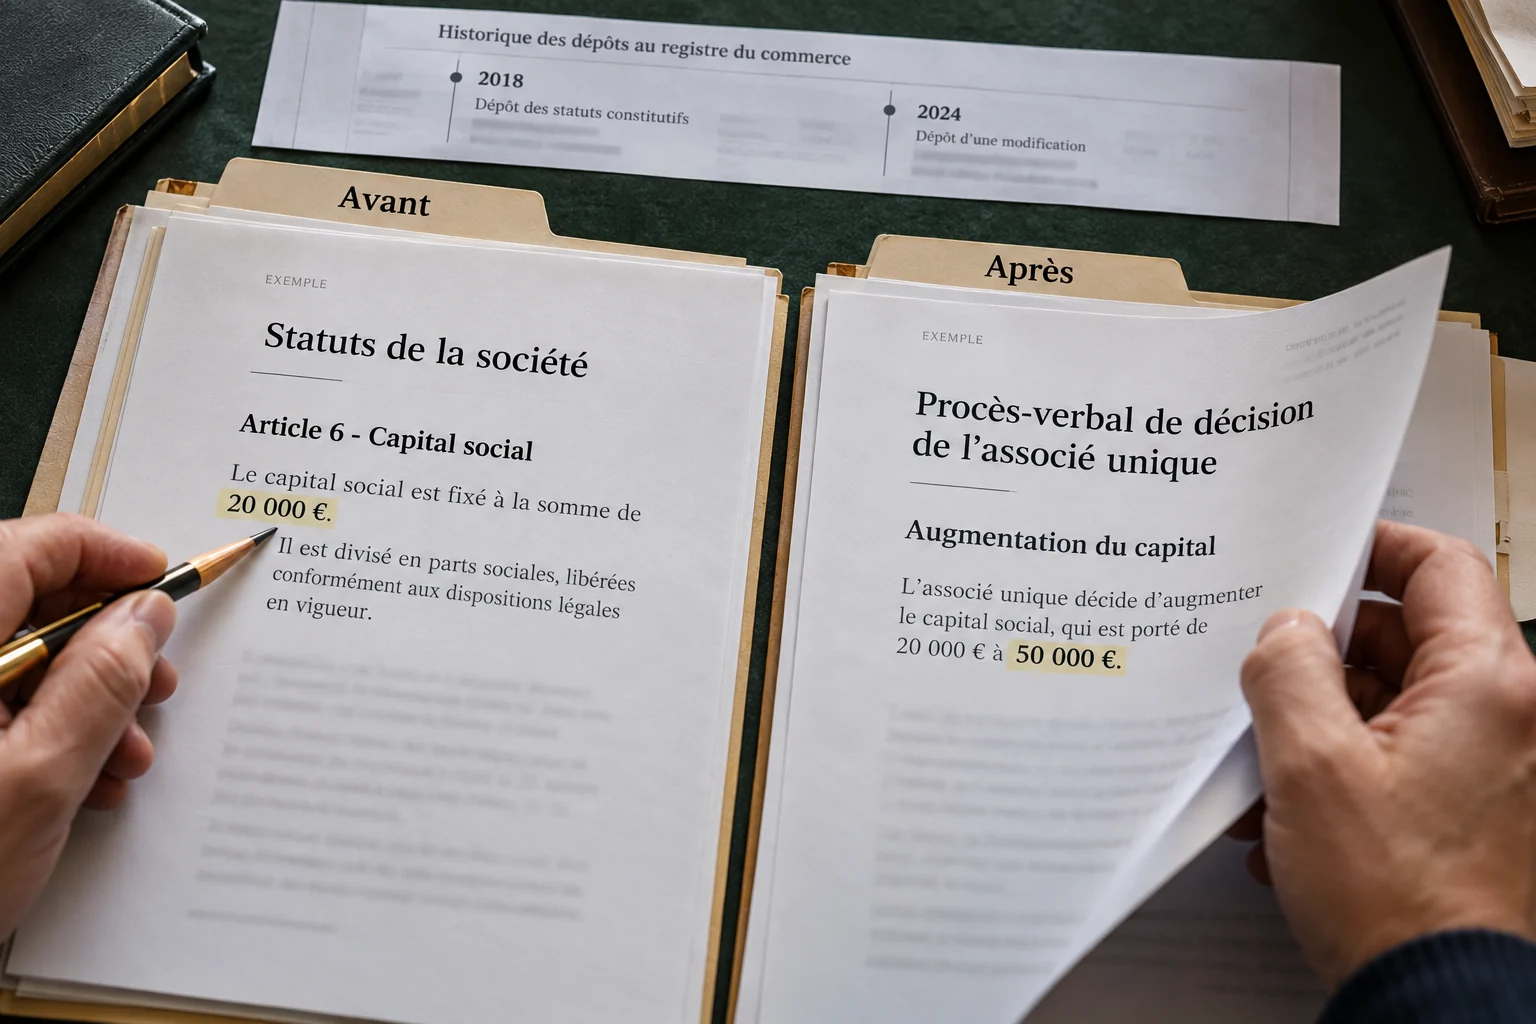
A capital event needs more than the headline total
Changes to share capital can involve allotments, reorganisations or other transactions with different effects. A filing may describe share numbers, classes, nominal values and amounts paid, so retain those fields rather than quoting an unexplained total. Historical figures should be interpreted in sequence and should not be added together as though every filing records new cash received.
Reconcile changes with later reporting
The Companies House forms collection identifies documents used for capital-related events. Initial formation information and confirmation-statement guidance provide the surrounding UK reporting context. Compare the change document with subsequent statements, noting any different currency or class structure, and investigate discrepancies before using the result to describe the company’s present ownership or financing.