
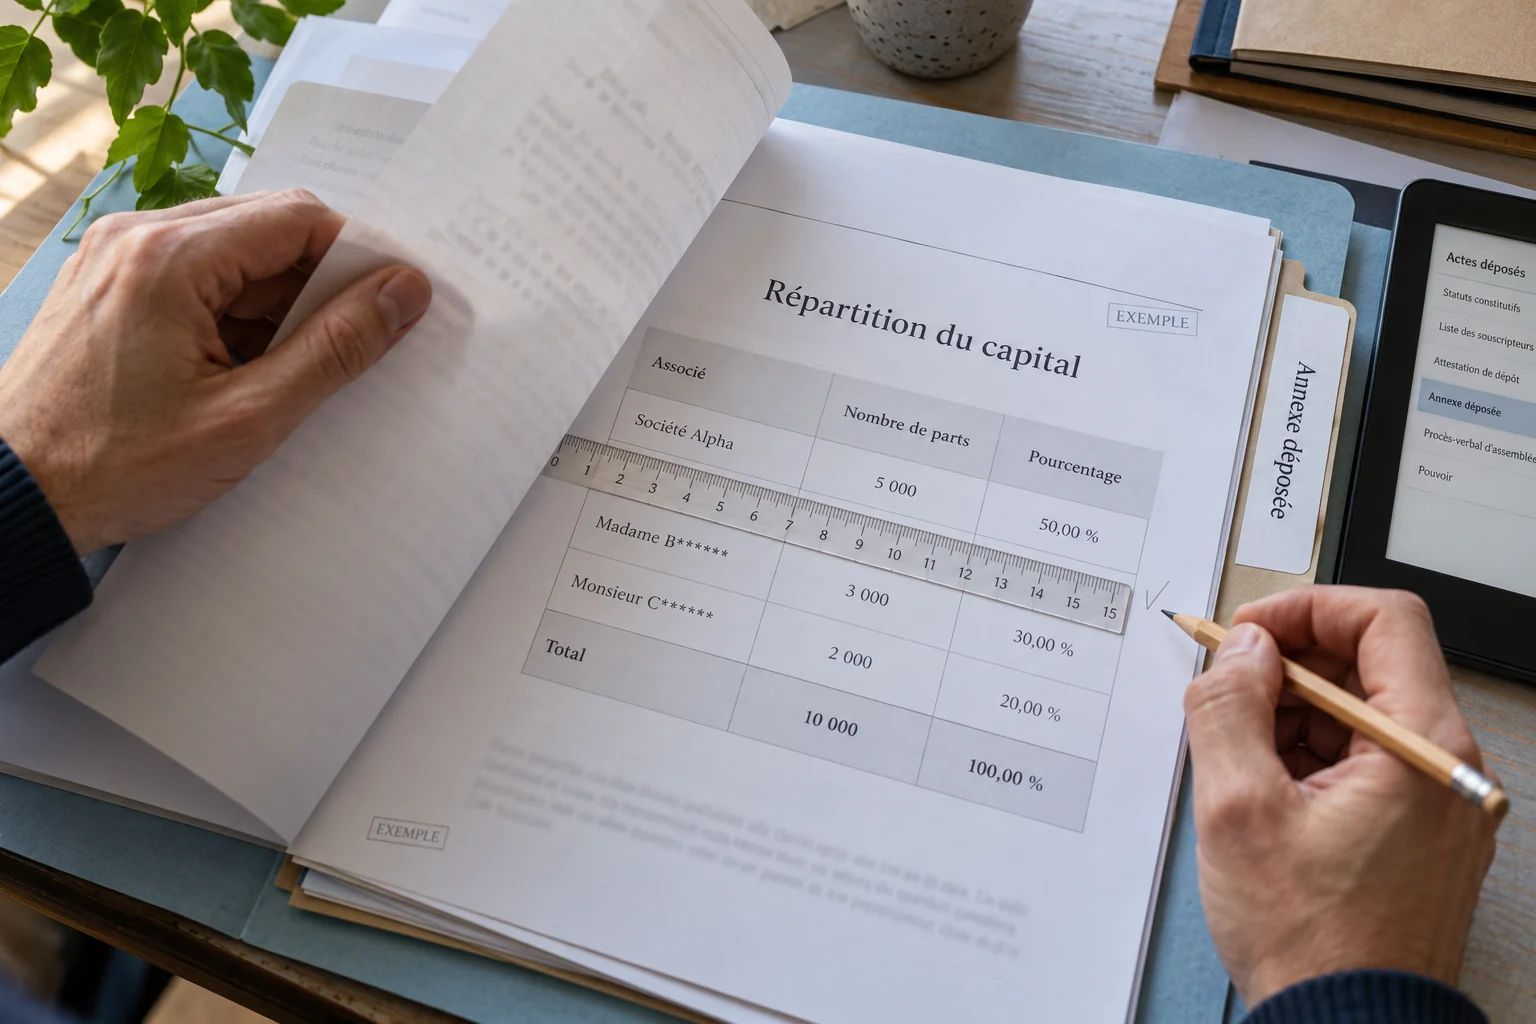
Define the relationship you are trying to establish
A parent company, a direct shareholder and an accounting consolidating entity may not be the same organisation. Subsidiary disclosures can also follow thresholds and reporting rules that vary between documents. Specify whether your enquiry concerns share ownership, control, consolidation or a branch relationship before combining records into a group chart.
Attribute every link to a dated source
GLEIF Level 2 data provides defined legal-entity parent relationships and may include reporting exceptions. SEC filings and published UK accounts can add group information within their respective disclosure frameworks. Label each relationship with its source and reporting period, and avoid drawing a complete group structure when the available filings support only selected connections.