Filed company accounts: balance sheets and annual reports at the registry
Filed company accounts are the annual accounts, balance sheets and profit and loss statements that a business deposits with a registry or another authority. Whether they are public, how detailed they are and who must file depends on the country and the size of the company.
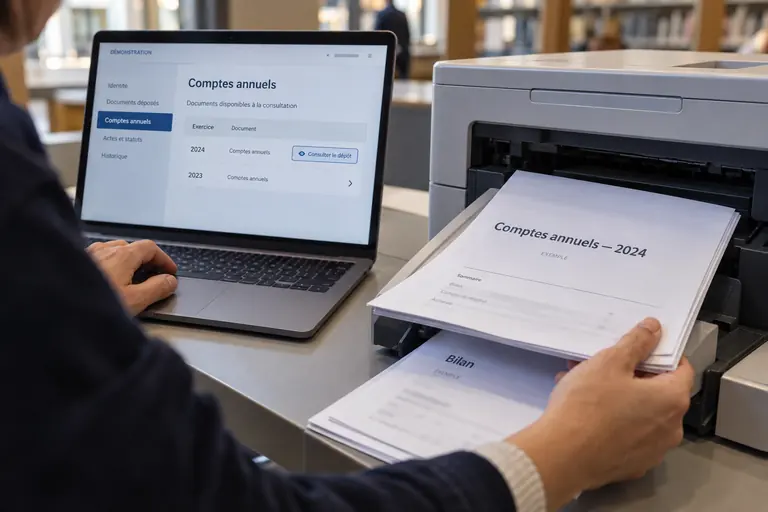
What filed company accounts are and why they are deposited
Filed company accounts exist because many legal systems require companies to prepare yearly financial statements and to make them available to the public. The aim is to protect creditors, investors and business partners who deal with an entity whose owners enjoy limited liability. In exchange for that protection, the company discloses information about its finances.
The filed company accounts typically include a balance sheet, a profit and loss account and explanatory notes. Larger companies may add a management report, a cash-flow statement and an auditor’s report. The package differs by country and by legal form.
Accounts are normally filed once a year, though listed companies may publish interim reports under separate rules. A deposit is not an approval. The authority that receives the accounts generally checks that the filing is complete and in the required format, and does not certify that the figures are correct. Responsibility for accuracy lies with the managers, and with the auditors where an audit is mandatory.
Who must file annual accounts with the registry
The obligation usually concerns capital companies such as limited liability companies and joint-stock companies. Partnerships, sole traders and associations are treated differently, and some are exempt unless they exceed certain thresholds or have limited-liability partners. The exact scope is a matter of national law.
Size matters in many countries. A micro-entity may be asked for little more than a short balance sheet, while a listed or public-interest entity faces demanding publication duties. Threshold values change with legislation, so older articles and forms may be outdated. Small companies often benefit from simplified reporting or from partial confidentiality, medium-sized ones file fuller documents, and large ones may need an audit and extra disclosures. The criteria, expressed in turnover, balance sheet total or staff numbers, are set locally and are updated from time to time.
Foreign companies operating through a branch can have to file the accounts of the parent, those of the branch or both. Groups may have to deposit consolidated accounts. These rules explain why a search for the accounts of a multinational may lead to several different entities.
Where annual accounts filed with the registry are kept
The place where filed company accounts are kept varies. In some countries the commercial register itself stores the accounts. In others a separate office is responsible, such as a central bank of balance sheets, a national gazette or a tax authority. The Norwegian Brønnøysund Register Centre, for example, keeps the Register of Company Accounts alongside other business registers.
Germany offers another model. Annual financial statements and similar publications are submitted for disclosure to the operator of the Bundesanzeiger and become accessible through the Unternehmensregister, the central platform for company data. Users there find filings, registered entries and notices from several registers in one place. The same logic applies in other countries that group disclosures on a single national platform, and it spares readers from visiting several offices.
In common-law systems, the registrar of companies normally receives the accounts and exposes them as document images attached to the record. In the United Kingdom, Companies House provides free access to document images on its information service, and the filing duty rests with the company.
Consulting filed company accounts
Consulting filed company accounts begins like any other registry search: identify the company by name or number, then look for the section on accounts, financial statements or documents. Some portals list each filing by year and let the user download it directly. Others require an order or a subscription.
Format varies among filed company accounts. Some countries impose a standard electronic taxonomy, and others accept ordinary documents in a portable format. Older filings may be scanned images, while recent ones may be structured electronic files that allow automatic analysis. Language follows the country, and a translation is rarely provided by the registry.
Access conditions are set locally. Free consultation, a modest fee for each document, a subscription, or restrictions linked to the size of the company are all possible. The conditions in force should be read on the official portal before relying on an assumption.
Filing deadlines, penalties and missing accounts
Filing deadlines for company accounts typically run from the end of the financial year or from the approval of the accounts by the members. The time allowed depends on the country and the kind of company, and extensions are available in some places. The rules are published by the competent authority.
Late or absent filing can have consequences. The amount of any penalty and the speed of enforcement differ strongly from one country to another, and some registries are far stricter than others. Registries may impose fines, apply a status mark such as default, or in the long run start a procedure to remove the company. Directors can in some systems be held personally liable.
For a user, a missing filing is itself information. In a search for filed company accounts, it may reflect a small exempt business, a newly created company whose first deadline has not yet passed, or a firm in trouble. Treat it as a question to investigate, not as an answer. Asking the company directly, or the registry about the filing status, is the natural follow-up.
Reading a balance sheet and profit and loss account from the registry
In filed company accounts, a balance sheet lists what the company owns and owes at a given date. Assets include fixed assets, stock, receivables and cash, while liabilities include debts, provisions and equity. Reading the notes helps to understand valuation methods, guarantees and commitments that do not appear in the headline figures.
The profit and loss account summarises income and expenses over the period. Comparing several years shows trends in activity and profitability. Exceptional items, changes of accounting policy and group restructuring can distort the comparison, so notes and comparatives should be read with care. Accounting standards differ by country, which makes direct comparisons across borders delicate.
Filed company accounts are historical. They describe a period that ended months before publication and say nothing about current trading. Small companies may also publish abridged versions, so the absence of a detail does not mean it does not exist.
Limits of filed company accounts as a source
Filed company accounts are prepared by the company and reflect accounting choices within the legal framework. They are not a credit rating, a valuation or a guarantee of solvency. For significant decisions, they should be read next to other information, such as payment behaviour, ownership, litigation and market conditions.
Confidentiality options exist for some small entities, which may deposit very limited data. Exemptions can also apply to certain regulated sectors, which report to supervisors rather than to the public registry.
This text offers general information on filed company accounts and does not constitute accounting or legal advice. A chartered accountant, an auditor or a lawyer in the country concerned can interpret the figures and explain the obligations that apply to a particular company.